16Sep11:25 amEST
Slow Playing It
With well over a 90% probability of The Fed hiking by 25bps later today, unless Kevin Warsh and the Committee intend to break an extensive pattern of following market expectations we can expect a higher Federal Funds rate by day's end.
However, as we noted yesterday and in recent videos for Members, there is a distinct possibility that 25bps may not be enough for the market to truly believe The Fed is serious in its efforts to fight inflation. While there is a counter-argument that this inflation is a supply shock due to oil and other commodities, the stark reality is that inflation has been well above The Fed's own (arbitrary) 2% target for more than five years. If one wanted to, one could cherry-pick any given data point as justification for not raising rates, including the supply shock red herring.
In reality, The Fed has been the bartender pouring easy money for all, including the federal government, enabling wild spending and the racking up of more than $40 trillion (with a "T") in debt. We can fault politicians from both sides of the aisle, the ultra-wealthy, the corrupt, and anyone else for getting drunk.
But without The Fed pouring booze so freely we would not be in the position we are today.
On that note, I still view gold as one of the best long-term plays against this backdrop. Even though the gold metal had a corrective first half of September, recall that it surged throughout most of August, in effect front-running the bullish September seasonality.
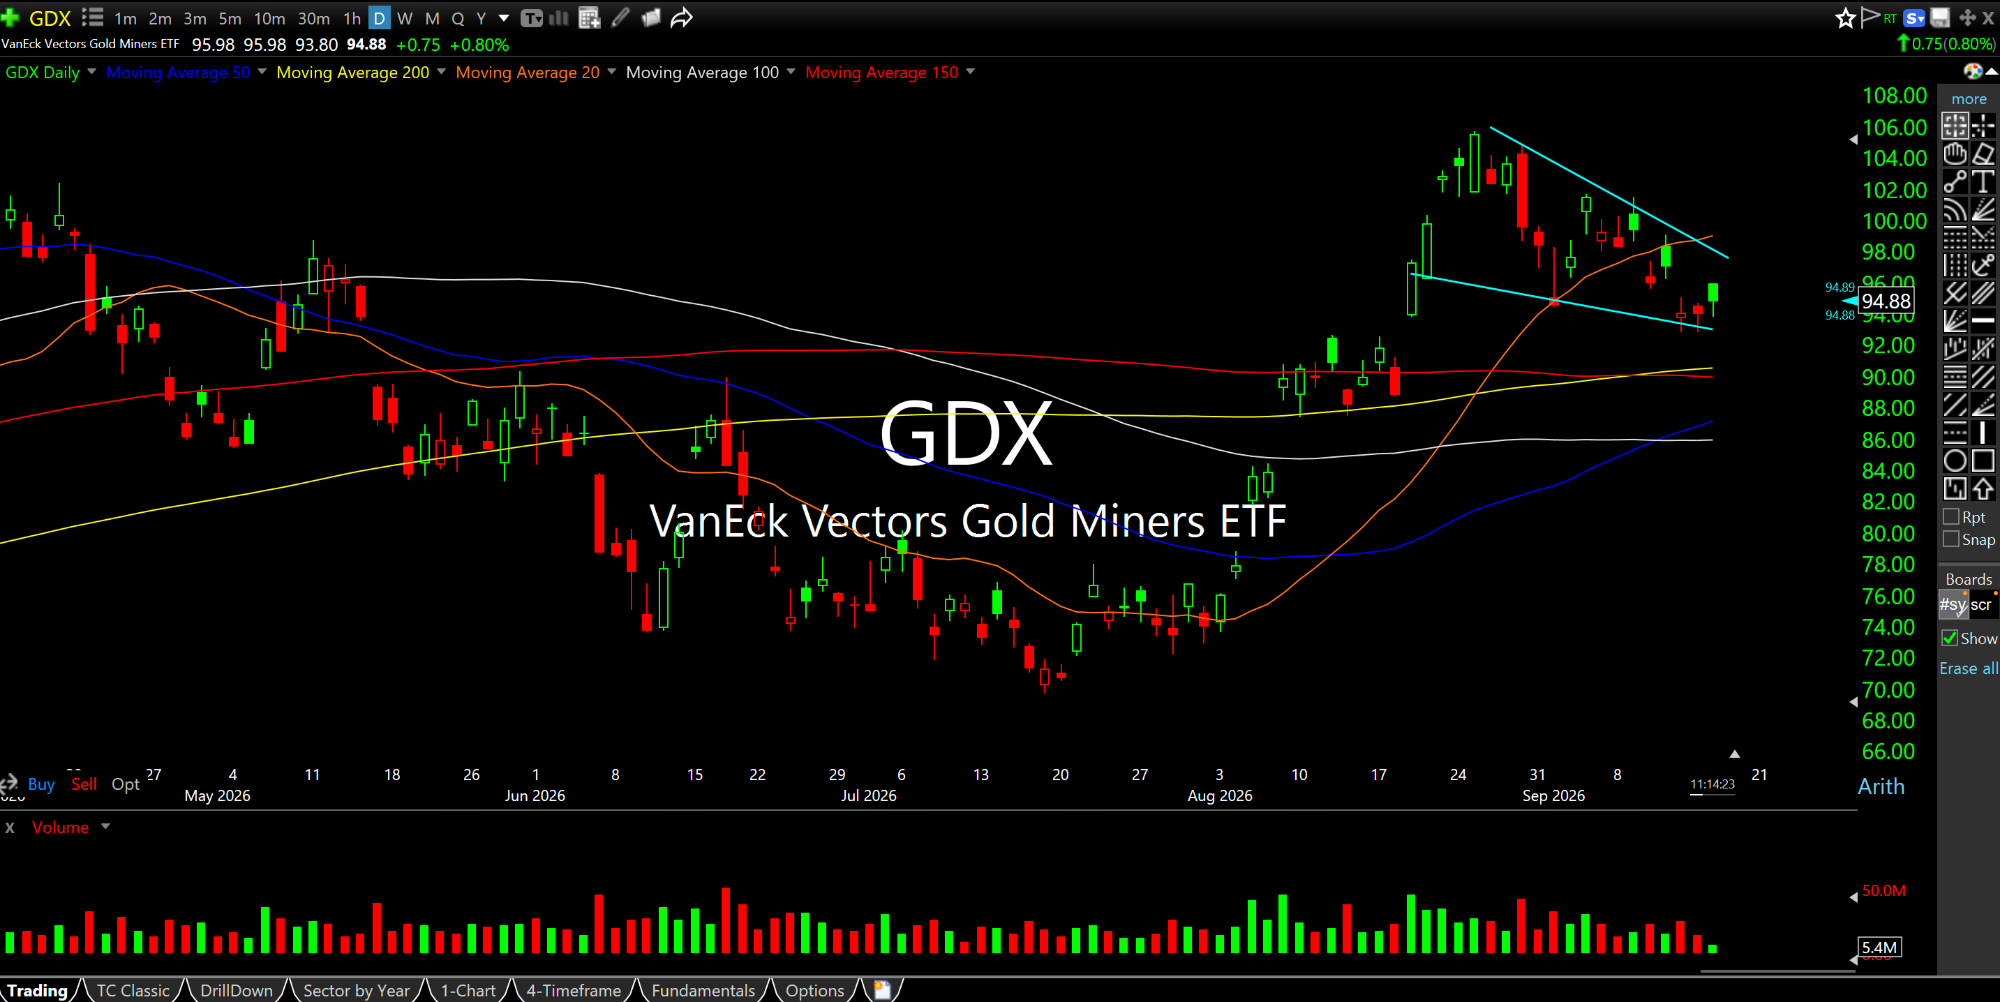
Also note the gold miners continue to operate smoothly, with a tight bull falling channel on the GDX ETF daily chart, below, above its 200-day moving average. Gold and the miners may very well be "slow playing" the early September consolidation to set up a new leg higher.
After all, if The Fed is going to hike, then why not go all the way and actually crush inflation? Jerome Powell did not have the guts to go all the way, and left us with a mirage of a soft landing in the form of entrenched inflation and a long line of apologists who keep begging for more time before we hike just in case inflation is transitory.
But this time the bond market, oil, and possibly gold may have lost patience. And those who know their history--especially the 1970s--know that those asset classes have the final say.